
Gross income is a before-deduction figure, but the deductions and calculation stage depend on whether the context is payroll, an individual tax return, or a business.
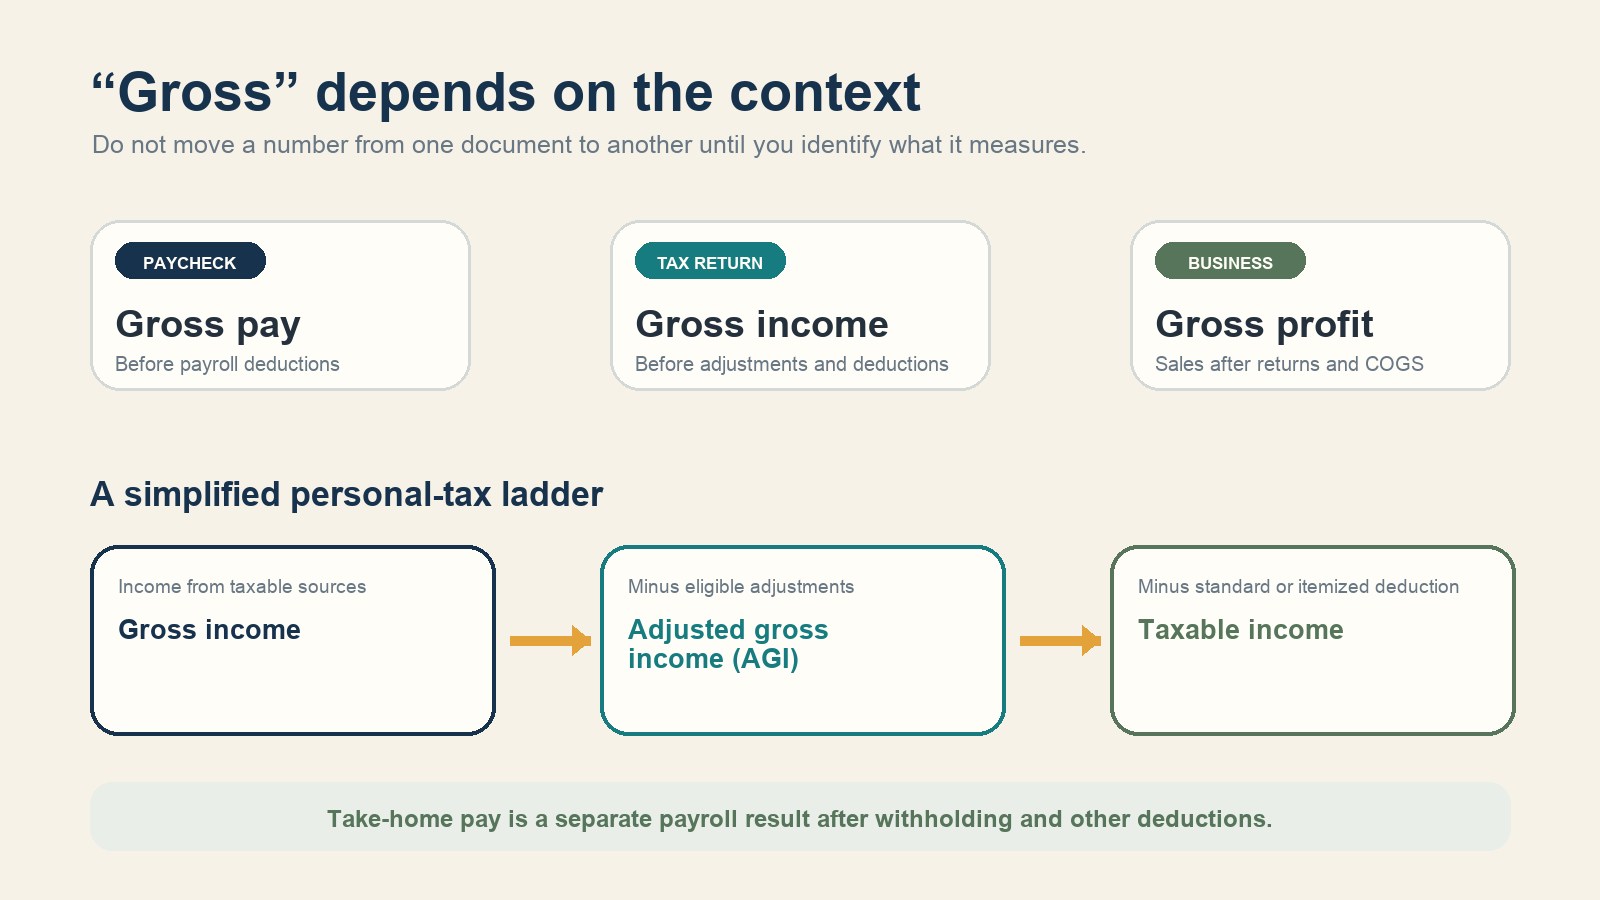
Gross income is income measured before certain deductions, but the exact meaning depends on the document. On a paycheck, gross pay is earnings before payroll withholding and other deductions. For US federal tax, gross income generally includes taxable income from all sources before adjustments and the standard or itemized deduction. For a product business, gross profit is net receipts minus cost of goods sold.
Those figures are related, but they are not interchangeable. Gross income is not automatically your take-home pay, adjusted gross income (AGI), taxable income, business revenue, or net profit.
First identify where the number appears
The word gross usually means “before something is subtracted.” The missing question is: before what? A paycheck, an income-tax return, and a business income statement subtract different things at different stages.
| Context | Gross usually means | What comes later |
|---|---|---|
| Paycheck | Pay for the period before payroll deductions | Federal and state withholding, employment taxes, benefits, and other deductions |
| Individual US tax return | Taxable income from included sources before eligible adjustments and deductions | Adjustments that produce AGI, then deductions that help produce taxable income |
| Product business | Gross profit after returns, allowances, and cost of goods sold | Operating expenses and other items that lead toward net profit |
This context check prevents a common error: copying the largest number visible on one document into a form that asks for a differently defined income figure.
Gross pay on a paycheck
In payroll, gross pay commonly means an employee’s earnings for a pay period before amounts are withheld or deducted. Salary, hourly wages, commissions, bonuses, and some taxable benefits may contribute, depending on the pay arrangement. The IRS’s current Employer’s Tax Guide describes wages as pay for services and explains that federal income tax is withheld from wage payments.
Suppose a payslip shows $3,000 of gross pay. After $450 of tax withholding, $230 of employment taxes, $120 of benefit deductions, and $50 of another authorized deduction, the employee receives $2,150. The gross pay is still $3,000; the take-home or net pay is $2,150.
Gross pay is useful for checking rate × hours, salary allocation, overtime, commissions, and bonuses. It does not tell you how much cash reached the bank, and it is not necessarily the same figure that appears as gross income on a federal return.
Gross income for US federal tax
The IRS defines gross income for filing purposes as income received in money, goods, property, and services that is not exempt from tax. Its filing guidance uses that definition when explaining who may need to file. Income can therefore exist even when no cash deposit or tax form arrives.
Common included categories can include wages, tips, interest, dividends, capital gains, business income, pensions, and other taxable receipts. IRS Publication 525 explains that income may be money, property, or services and is generally taxable unless a law specifically excludes it. The category and calculation rules matter: for example, a sole proprietor generally brings net business income, not raw customer receipts, into the individual-income calculation.
Gross income, AGI, and taxable income are different
For an individual federal return, the simplified sequence is:
- Gross income: combine income that tax rules include, using the required calculation for each category.
- Adjusted gross income (AGI): subtract eligible adjustments to income.
- Taxable income: continue with the standard or itemized deduction and any other applicable rules.
The IRS’s AGI definition says AGI is gross income from all sources minus specified adjustments, and it is calculated before the standard or itemized deduction. The agency’s taxable-income guidance also notes that most income is taxable unless an exemption applies—even if the payer did not issue a reporting form.
AGI is frequently used for tax thresholds and eligibility tests. Taxable income is the later amount to which tax rates generally apply. Take-home pay belongs to payroll and follows a separate path. Treating all four as synonyms can change the result of a form or eligibility check.
Gross income for a business can mean gross profit
Business language adds another distinction. For a business that sells products, gross receipts are customer receipts before returns and allowances. Net receipts are gross receipts minus returns and allowances. Gross profit is then generally net receipts minus cost of goods sold (COGS).
The IRS Tax Guide for Small Business describes that sequence, while the current Schedule C instructions separate gross receipts, returns and allowances, COGS, gross profit, and later business expenses. Gross profit therefore is not the same as revenue and is not the same as net profit.
A service business without inventory may have little or no COGS, so its gross-income calculation can look different. Always follow the accounting and tax definitions that fit the activity rather than forcing a retail formula onto every business.
Two worked examples
Personal federal-tax example
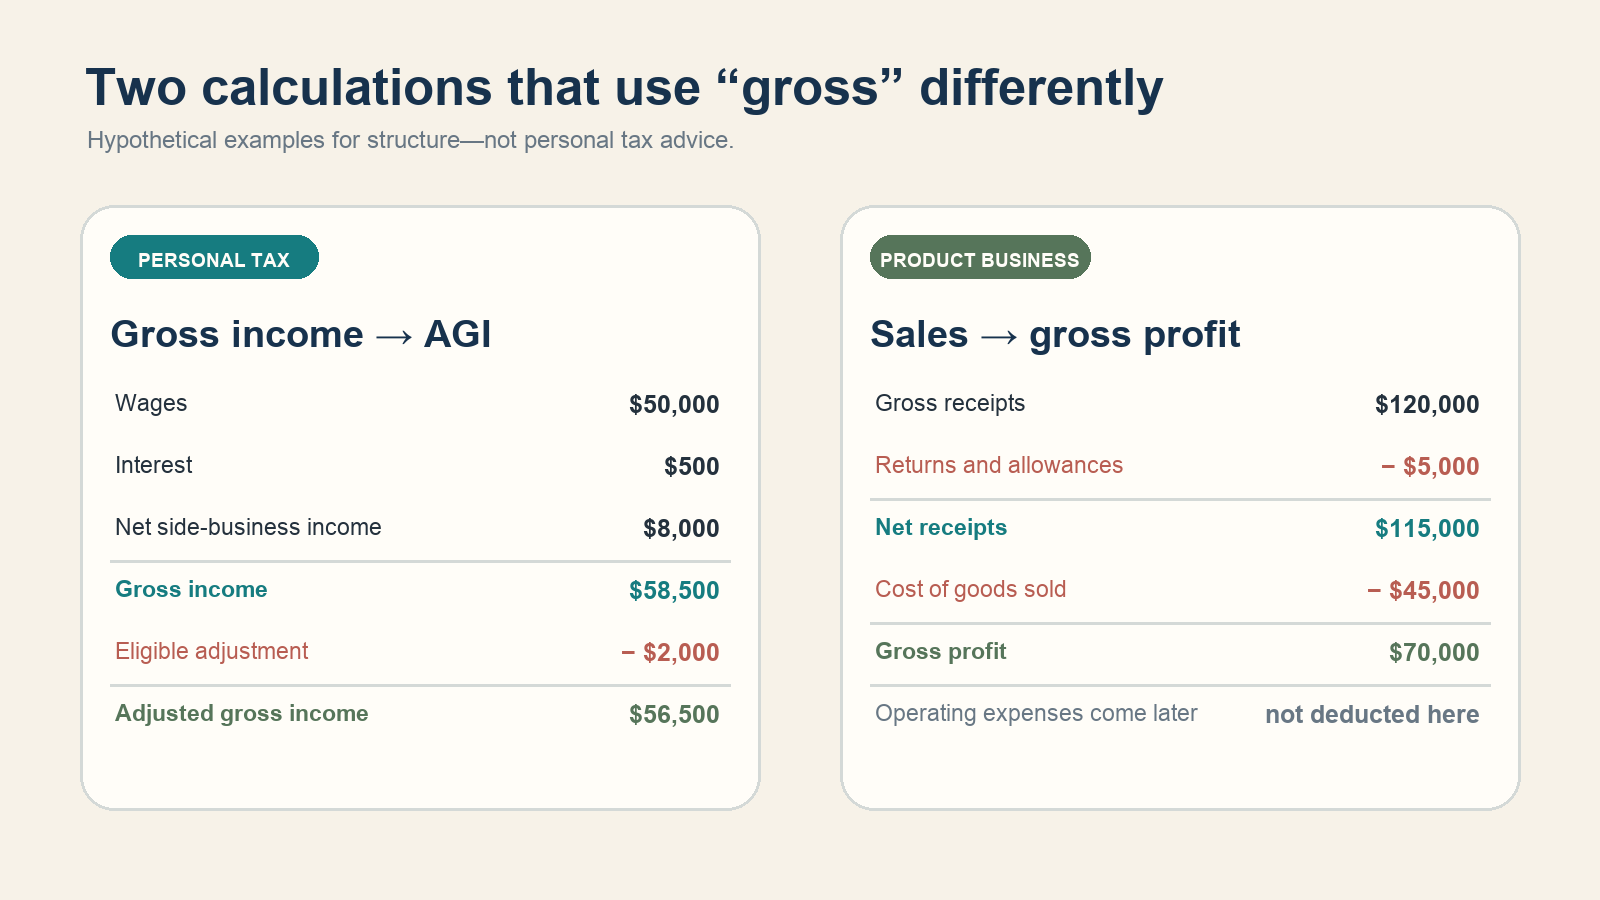
Assume a person has $50,000 of wages, $500 of taxable interest, and $8,000 of net income from a side business. For this simplified example, gross income is $58,500. If that person has a $2,000 adjustment that is eligible under current rules, AGI becomes $56,500. The applicable standard or itemized deduction is considered later; it should not be subtracted when answering a question that specifically asks for AGI.
The phrase net income from a side business is important. If the business collected $20,000 but had deductible business costs, $20,000 is not automatically the amount carried into this simplified personal calculation.
Product-business example
Assume a shop records $120,000 of gross receipts and $5,000 of returns and allowances. Net receipts are $115,000. If COGS is $45,000, gross profit is $70,000. Rent, advertising, payroll, software, and other operating expenses have not yet been subtracted from that $70,000, so it is not net profit.
Common mix-ups to avoid
| If a form asks for… | Do not automatically enter… | Check instead |
|---|---|---|
| Monthly gross pay | The bank deposit | The pay-period earnings before payroll deductions; convert periods only as instructed |
| Annual gross income | One paycheck multiplied without checking bonuses or variable hours | The form’s definition, time period, and included income sources |
| AGI | Gross wages or take-home pay | The AGI on the applicable federal return or a current calculation |
| Business revenue | Gross profit or net profit | Whether the form wants gross receipts, net receipts, or another revenue measure |
| Business gross income | Cash collected from customers | Returns, allowances, COGS, and the tax form’s instructions |
Which income number should you use?
Read the exact label and any definition supplied by the requester. A landlord, lender, benefits program, tax form, and accounting report may use similar words but specify different inclusions, exclusions, and periods. Then match the request to the correct evidence:
- Use a pay statement for pay-period gross pay and deductions.
- Use the requested tax return line for AGI or taxable income, not a guessed substitute.
- Use bookkeeping reports and the applicable tax instructions for business receipts, gross profit, or net profit.
- Confirm whether a monthly figure means one pay period, a calendar-month total, or annual income divided by 12.
The safest rule is simple: identify the context, locate what has already been subtracted, and stop at the requested stage. Tax definitions and thresholds can change, and unusual income may follow special rules. For a filing decision or material financial application, check the current IRS instructions and the requester’s definition, or consult a qualified tax professional.